Most investors spend their energy hunting for the next winning fund. Far fewer examine the quiet line item that trims every dollar they earn: cost. Fees are one of the few parts of investing you can actually control, and their damage compounds just like returns do. This article looks at how much they really matter and how to keep them in check.
The Math Behind a “Small” Percentage
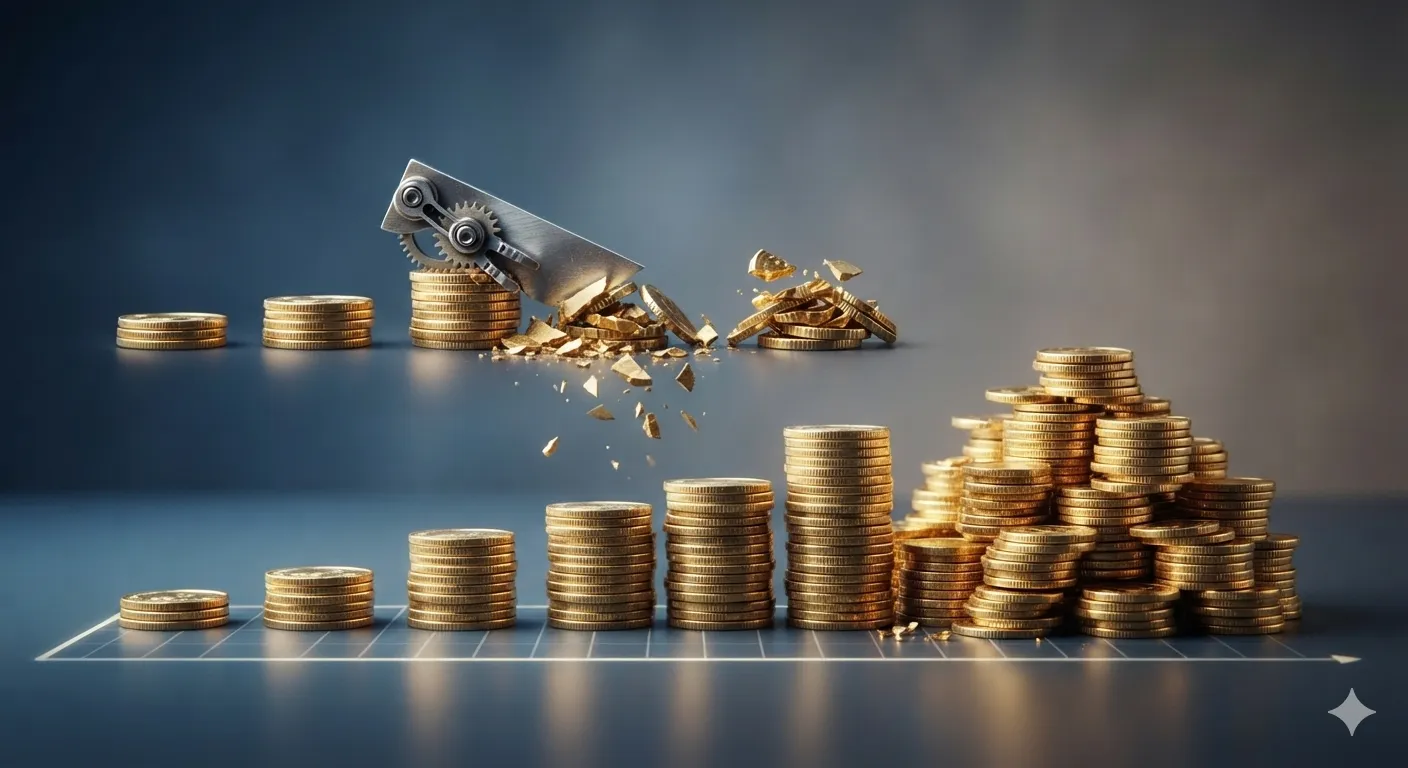
A 1% annual fee sounds trivial. But it is charged on your entire balance every year, whether markets rise or fall, so the dollar amount grows right along with your portfolio and never takes a year off.
Picture a hypothetical $10,000 held for 30 years with a 6% annual return before costs. With a 0.1% fee, it grows to roughly $55,800. With a 1% fee, it reaches about $43,200, a gap of more than $12,000. This is an illustration only and ignores taxes, inflation, and market swings.
What the Research Shows
Morningstar tested this idea by sorting funds into five groups by expense ratio and tracking results over the five years ending in December 2015. A fund counted as a success only if it both survived the period and beat its peers, which makes the test a tougher one.
Among U.S. stock funds, the cheapest group posted a 62% success rate, compared with just 20% for the most expensive group. The researcher behind the study called the expense ratio the most proven predictor of future fund returns, and suggested treating cost as a first or second screen when choosing funds.
Why Time Makes It Worse
Compounding works in both directions. Money lost to fees today is money that can no longer earn returns tomorrow, so the costs you pay early carry the heaviest long-term price tag of all. Every dollar paid in fees in year one has decades of lost growth attached to it.
That is why younger investors who add money every month feel the effect most. A difference of half a percentage point may look invisible this year, yet across decades of steady contributions it can add up to a surprisingly large sum that never reaches your account.
Costs That Hide in Plain Sight
The expense ratio is only part of the story. Trading commissions, currency conversion charges, account maintenance fees, and bid-ask spreads can all take their own bite out of your results, and most of them never appear on a headline price list.
These charges often sit deep inside fee schedules. A fund with a low expense ratio can still turn expensive if the platform you use charges heavily for every trade, so total cost deserves a full look before you commit any money to it.
A Simple Cost Checklist
Before buying any fund, look up its expense ratio and compare it with similar funds in the same category. Then use a comparison resource such as Finpilot.sk to see how trading, currency conversion, and inactivity charges stack up, and write the totals down so they are easy to review.
Next, ask whether the strategy justifies the price. Index funds, which simply track a market benchmark, generally cost less than actively managed funds, and active managers must beat the market after fees just to match the cheaper option. Whether that extra cost is worth paying is a question every investor should ask.
Keeping Cost in Perspective
Low cost does not mean low risk. A cheap fund can still drop sharply in a bear market, and no amount of fee savings can fix poor diversification or panic selling during a downturn. Cost is one tool, not the whole toolbox.
Think of cost as the one variable you can lock in ahead of time, since a fund’s fee is published before you buy. Review your total costs once a year, ideally on a set date, then put your remaining effort into your savings rate, your diversification, and your time horizon.
Final Thoughts
Fees rarely make headlines, yet over several decades they can rival the impact of market swings. A yearly review takes little time, costs nothing, and can meaningfully improve how much of your return you actually keep in the end.
Knowing what you pay is the first step toward keeping more of what you earn, and the calculators and comparison tools at Finpilot can help you run the numbers for your own situation.